Zoom – The Tesla of Meetings
From the 11ish archive: written in August 2020. Prices, numbers and views are from then and are not investment advice today.
In this article, we’re going to talk about why Zoom is not overvalued, why I sold my entire Disney stake and put all of it into Zoom instead, and how it might fit into your portfolio for the next 3 to 6 months.
If you’ve been following me since the beginning, first of all, thank you; I really appreciate your support and kind words that motivate me to keep going.
More importantly, my original hypothesis at the start of COVID that remote office productivity will be a breakout industry has worked out better than ever expected. Now that COVID has extended longer than anyone has ever initially imagined and a bunch of new money is now helping us make gains faster than ever before, it’s starting to feel like shooting fish in a barrel.
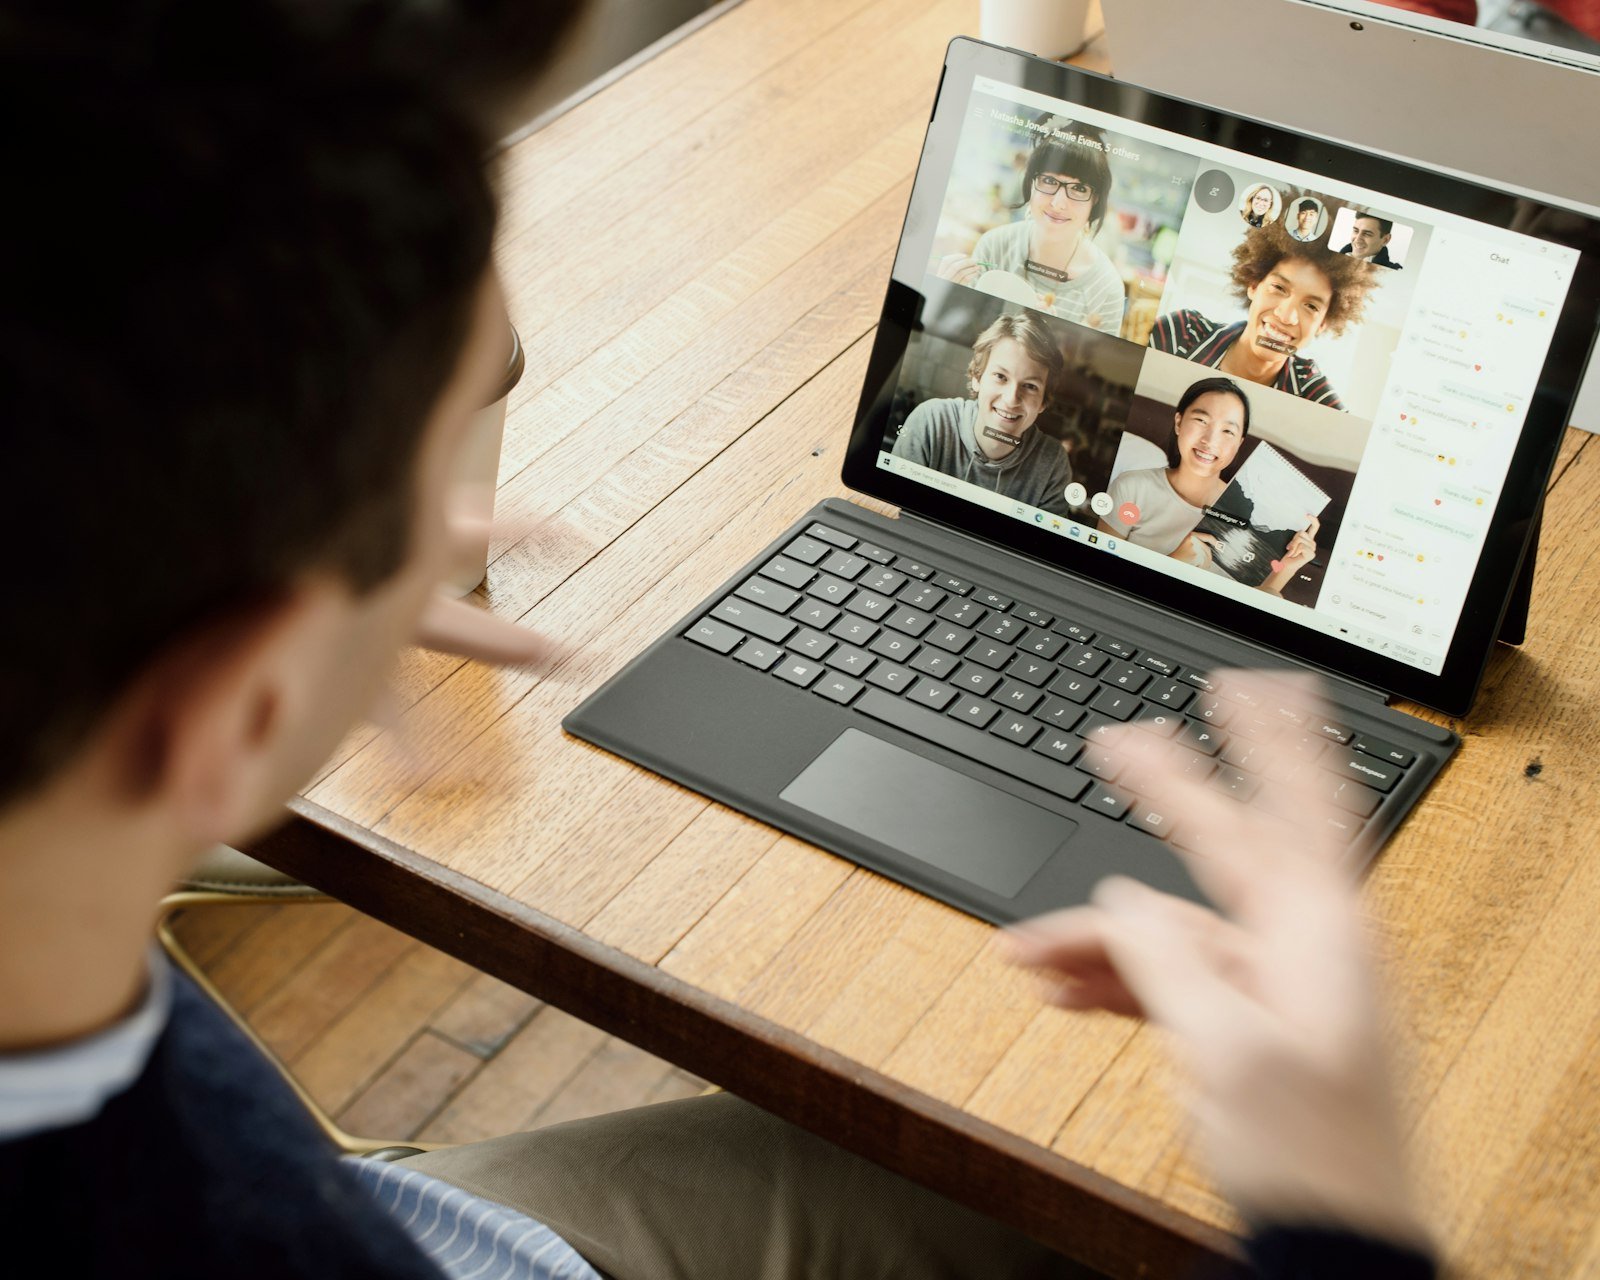
Zoom is a web conference tool that is in the hot seat to kick ass and here are the reasons why.
Leadership
I like the leadership. When I invest in stocks, I make it a point to know the leadership. It just so happens that I was at a tech conference where the CEO of Zoom was being interviewed, and he talked about how Zoom originated from an idea he had while commuting by train when he was younger, doing whatever it takes to line himself up for success. All the while he wanted a better way to connect and communicate with his girlfriend and there were no tools that met his standard. This tells me that he is passionate about what he’s building and he’s committed to success. I also gleaned from the interview that he really cares about the people that work for him. It ALWAYS bothers me when I’m researching about a business and learn that all the leadership cares about is not brand love, nor legitimate value advantages that help capture more users and markets, but how to get more money.
Technology
It’s the technology. And by that I mean stability and user experience. You’d think the technology beneath all of these companies is the same with a very small technological delta. You’d think that it’s all about how deep the pockets are and who you know to grow a business as simple an idea as video conferencing. But that’s just not the case. The company has been basically doubling its top line YoY which is sexy as fajita, and being in the tech industry myself, working with teams from Poland, Australia, London, New York and have used basically every type of web conference tool ever built for B2B, I can honestly say I think Zoom has the best product hands down.
HOWEVER, I chose not to invest in Zoom at the time because right when I was about to pull the trigger, Zoom got slammed by news about security issues and I thought people are going to freak the fajita out and it’s going to be an uphill battle trying to regain consumer confidence. Lo and behold businesses of all sizes still schedule meetings with me through Zoom. Zoom’s top line still looks sexy as fajita and I missed out on a LOT of gains.
COVID Benefits
Because of COVID and seeing a ton of office productivity tools blow up in the last few months not just because of hype but also because of legitimate quantifiable business value, I am now more confident than ever to invest in Zoom. But there are also 3 more business indicators I’d like you to notice.
- Amidst all of the security issues that they are dealing with, since January, Zoom has seen a 65-fold increase in users of its free service in Singapore as well as a tripling of the amount of paying customers in the region. If that is not an indication for market fit, I don’t know what is. Furthermore, we know Southeast Asia is an emerging market for all things eCommerce and Tech so I am highly keen on taking a look at anyone diving head first in that direction of the world.
- The 2nd indicator is that according to LinkedIn and Glassdoor, Zoom has 3500 employees and 360 job recs. When most companies are firing, this is an incredibly healthy indication that this company is growing their asses off. It is also interesting to me that they are hiring a Product Manager for Marketplace. Companies tend to do this when they want to tackle niche features but don’t have resources to build one-off solutions themselves. A marketplace is also a great approach to allow business verticals to reveal themselves so that your internal teams know where to focus.
- The 3rd indicator is that they’re doing a Facebook integration and that will lead to CONSUMER centric appeal which is really fajita-ing smart. Most B2B solutions have a top down approach, where you build tools that satisfy the checklist of CTOs and the likes, because if you can convince the guy that pays for the solution, the end user’s complaints frankly don’t matter too much. Zoom is obviously doing well on that front but is now also taking the bottom up approach, where you make your tool available to end users first and then when businesses are looking for tools they’re like my end users are already using this, if I buy the tool for the business it’ll be a shoo-in. So this is music to my ears that Zoom is doing this.
I can go on and on about Zoom because I definitely drank the kool-aid, but I do have 1 single major concern.
- It’s that their PE ratio is higher than Tesla’s. In a healthy market, most SaaS companies are floating between 20 and 100. Similarly, Zoom’s price-to-sales ratio is 100 and Slack’s is 20. The higher these numbers are, the more optimistic people are that the company will grow in an explosive way. For example, MSFT and Apple’s PE ratio is around the mid-30s. Zoom is currently 1700. This ESSENTIALLY means if Zoom shows ANY hint of slowing down their current ridiculous growth projection or if the CEO for some reason voices caution this stock has a reasonable potential for an adjustment.
Summary
All in all, with the extensions to COVID and the inevitable changes to how people work, EVEN if we were allowed back into the office, remote conferencing tools will grow well and Zoom’s competitors still have a ways to go. With hedge funds buying ZM andMorgan Stanley and RBC recently updating their sentiments to equal weight and outperform and the high-end of the analyst price target being 30% more than where it currently is, I’m reasonably comfortable with my new investment through earnings.
Alright everyone, I hope you found this information useful and if you did please share it with your friends so that we can continue to grow the 11ish collective together.
If you have any questions or concerns please leave a comment and if you have any requests please hit that subscribe button then leave me a note. Thanks for reading, and I look forward to working with you next time.
Disclosure: As of October 3, 2026, the author holds ZM. No payment was received for this post. This is commentary from August 2020, not investment advice. Zoom is an investor in Anthropic, the company behind Claude, the AI that helped edit this archive.